

Blogs
PW Consulting: Mesalazine Market Hits $215M in 2025, Projects 3.7% CAGR Through 2032
By PW Consulting, 2026-09-16
Unlocking the Mesalazine Market: Strategic Intelligence for the 2026–2032 Horizon
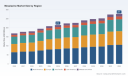
As inflammatory bowel disease (IBD) continues to impose a growing clinical and economic burden across global healthcare systems, the mesalazine (mesalamine) market stands at a critical inflection point. Between 2020 and 2025, the market expanded steadily from approximately 169.0 million USD to 215.0 million USD, reflecting sustained demand for first-line aminosalicylate therapies and the gradual maturation of regulatory pathways for generic entry. Looking ahead, our latest market research projects the global mesalazine market to reach 224.36 million USD in 2026, with a compound annual growth rate of 3.7% driving the sector toward 277.0 million USD by 2032. For pharmaceutical executives, commercial leaders, and supply chain strategists, these figures are more than macro indicators. They are signals of where capital, regulatory attention, and competitive friction will concentrate over the next seven years.
This article serves as a strategic preview of our comprehensive Mesalazine Market report. It outlines the structural dynamics shaping the sector, highlights the competitive and regulatory forces that will dictate performance in 2026 and beyond, and explains why data-driven scenario planning is no longer optional for firms operating in this space. The full report provides a granular, decision-ready intelligence package. What follows is designed to demonstrate the depth of our analysis while preserving the proprietary segmentation and modeling details that you will need to access directly to build your own action plans.
Why 2026 Demands a Fresh Strategic Lens
The 2026–2032 forecast window is not merely an extension of historical trends. It is a period defined by overlapping shifts in clinical practice, regulatory volatility, and supply chain economics. Over the historical period from 2020 to 2025, the market demonstrated a consistent upward trajectory, with annual revenues climbing from 177.59 million USD in 2021 to 208.96 million USD in 2024, before settling at 215.0 million USD in 2025. This pattern reflects a market that has moved past early-cycle adoption and is now navigating the complexities of generic proliferation, formulation differentiation, and regional supply constraints.
For decision-makers, the strategic question in 2026 is no longer whether mesalazine demand will grow, but how to position product portfolios, sourcing strategies, and regulatory engagement to capture value in a market that is simultaneously expanding and fragmenting. Our report is built around that question. It translates top-line growth into actionable intelligence across dosage forms, clinical applications, and geographic markets, while explicitly mapping the risks and opportunities that generic competition, shortages, and tariff-driven cost pressures introduce into forecasting models.
What Our Research Delivers: Operational Intelligence Beyond Headlines
A market study earns its place in a strategic planning cycle only when it equips teams to make concrete decisions. Our Mesalazine Market report is structured to move beyond narrative description and deliver operational precision. The analytical framework covers the full value chain, from active pharmaceutical ingredient (API) sourcing and regulatory filings to finished dosage form commercialization and patient-level demand drivers.
Mesalazine Market
At the core of the report is a multi-dimensional segmentation architecture that decomposes market size by dosage form, clinical application, and region. Rather than presenting isolated percentage splits, the analysis integrates these dimensions into a cohesive view of where volume concentrates, how formulation preferences vary across indication profiles, and why certain markets exhibit faster revenue conversion than others. This integrated approach allows commercial teams to stress-test product positioning, evaluate go-to-market timing, and identify underserved niches without relying on blunt aggregate metrics.
Equally important is the report’s treatment of competitive dynamics. The mesalazine sector features a diverse ecosystem of API specialists, formulation manufacturers, and branded product owners, many of whom operate across overlapping regulatory territories. Our analysis maps these players not simply by revenue share, but by manufacturing capability, certification portfolios, geographic reach, and recent market actions. That mapping is essential for understanding where supply resilience is strong, where single-source dependencies create exposure, and where new generic entrants are reshaping pricing and access expectations.
The report also incorporates a forward-looking regulatory and supply chain overlay. This includes tracking of recent FDA approvals, European Medicines Agency procedure outcomes, documented product shortages, and trade-policy developments that influence API cost structures. By embedding these variables into the market narrative, the research enables scenario planning that reflects real-world friction rather than idealized linear growth.
Competitive Landscape: From API Specialists to Branded Formulators
The mesalazine competitive landscape is best understood as a layered ecosystem. At the foundation sit API manufacturers and bulk suppliers whose certification portfolios and capacity footprints shape the cost and availability of the active ingredient. Firms such as PharmaZell, Zhejiang Hengkang Pharmaceutical Co. Ltd., LGM Pharma, Metrochem API Private Limited, IOL Chemicals and Pharmaceuticals, CTX Lifesciences, Syntese A/S, Ajinomoto OmniChem N.V., and Zydus Lifesciences represent a broad geographic spread across Europe, China, the United States, and India. Their common thread is a focus on mesalazine API supply supported by regulatory documentation including USDMF and CEP filings, which facilitates cross-border distribution and reduces friction for downstream formulation partners.
Above this API layer, branded and generic finished-product companies compete on formulation technology, release mechanisms, and clinical positioning. Ferring Pharmaceuticals and Tillotts Pharma AG have historically anchored significant branded presence through products such as Pentasa, Mezavant, and Asacol, building recognition in ulcerative colitis and related indications. At the same time, generic entrants such as Amneal Pharmaceuticals Inc. have expanded access through product launches referencing established branded benchmarks, including Amneal’s 2025 introduction of mesalamine 800 mg delayed-release tablets aligned with ASACOL HD for moderately active ulcerative colitis in adults. DifGen Pharmaceuticals further intensified competitive pressure in 2025 when it received FDA approval for generic mesalamine extended-release capsules in 250 mg and 500 mg strengths.
This layered structure creates a market in which competitive advantage does not come from a single lever. API reliability, regulatory timing, formulation differentiation, and supply continuity all interact. For example, branded players must navigate the growing availability of generic alternatives while maintaining inventory resilience, especially when documented shortages affect key dosages. Generic manufacturers, conversely, must manage the tension between volume ambitions and the operational realities of API sourcing, regulatory approvals, and intermittent supply disruptions. The report evaluates these interactions in detail, offering a competitive map that goes beyond simple company listings and instead highlights where strategic pressure is building.
Market Dynamics: Regulation, Shortages, and the New Cost Environment
No analysis of the mesalazine market in 2026 can ignore the operational realities introduced by recent regulatory actions, supply interruptions, and trade-policy shifts. These factors are not peripheral; they are central to forecasting accuracy and strategic risk management.
One of the most visible disruptions has been the intermittent shortage of established mesalazine formulations. In 2025, the marketing authorisation holder Tillotts reported shortages of Asacol 400 mg and 800 mg enteric-coated tablets, a development documented by the Finnish Medicines Agency. Such shortages matter because they affect prescribing continuity, patient trust, and the competitive balance between branded and generic options. The situation also illustrates how localized supply constraints can propagate across markets when a widely used dosage form experiences demand-supply misalignment. Compounding this, broader shortage dynamics have extended into 2026, with reports indicating that generic mesalamine extended-release capsule availability remains constrained with no clear resupply timeline in some channels. For manufacturers and purchasers alike, this underscores the importance of mapping shortage-prone dosages against inventory strategies and alternative sourcing paths.
Regulatory activity is moving in parallel. The European Medicines Agency procedure PSUSA/00001990/202402 for mesalazine concluded with a variation in November 2024, reflecting ongoing regulatory oversight of quality, comparability, and documentation standards across the supply base. For companies engaged in API supply or generic development, such procedures are not abstract compliance events. They influence submission timing, inspection readiness, and the pace at which new product versions can be commercialized. The report integrates these regulatory milestones into the forecast framework so that clients can anticipate approval cycles and compliance burdens rather than react to them.
On the cost side, the API supply chain has faced renewed pressure from trade-policy developments. As of 2025, U.S. Section 301 tariffs and additional reciprocal tariffs on Chinese imports have increased costs for API supply chains, a reality highlighted by suppliers including LGM Pharma. Because mesalazine production depends on intermediary chemistry and cross-border material flows, tariff exposure can affect margin structures, sourcing decisions, and the relative attractiveness of different manufacturing geographies. The analysis treats these cost pressures as a variable that can alter both pricing expectations and regional supply preferences, especially when firms reevaluate concentration risk in their supplier base.
Taken together, these dynamics create a market environment in which growth is real but uneven. Multiple generic approvals and launches have expanded competitive intensity, yet supply interruptions and regulatory variation continue to introduce volatility. For strategy teams, the implication is clear: forecasting should be built on scenarios that incorporate shortage risk, regulatory timing, and cost transmission, rather than on a single baseline trajectory.
Why This Research Matters for 2026 Decision-Making
The value of a market study lies in its ability to reduce uncertainty in the decisions that follow. In the mesalazine sector, that means helping leaders answer questions that are immediate and practical. Where is demand likely to be most resilient over the forecast period? Which dosage forms and indication segments concentrate volume and why? How should API sourcing strategies adapt to tariff exposure and certification requirements? Which competitive moves by branded and generic players are likely to reshape pricing and access in the near term?
Our report is designed to support those decisions with structured data and analytical clarity. It provides a historical foundation covering 2020 through 2025, a forecast framework extending to 2032, and a market concentration profile that helps assess the degree of competition and supplier dependency across the value chain. It also connects macro trends to operational implications, such as the need to evaluate shortage exposure in key formulations, the strategic relevance of USDMF and CEP certifications in enabling international supply, and the importance of monitoring regulatory procedure outcomes that can accelerate or delay market entry.
Because the full segmentation architecture, regional and application-level breakdowns, and proprietary scenario modeling are central to the report’s decision-support function, the deepest analytical layers are reserved for the complete document. The objective is straightforward: give you enough evidence of rigor and relevance here to confirm the study’s fit for your planning cycle, while preserving the detailed intelligence that should inform your final strategy.
How to Use This Report in Your Next Planning Cycle
For commercial leaders, the report can anchor portfolio prioritization by clarifying where volume concentrates and how formulation type and indication profile shape demand trajectories. For supply chain and procurement teams, it offers a basis for evaluating supplier diversification, certification alignment, and tariff-sensitive sourcing decisions. For regulatory and market access stakeholders, the inclusion of recent FDA actions, EMA procedure outcomes, and documented shortages supports more realistic planning around launch timing, inventory buffers, and contingency sourcing.
The research is equally useful for competitive intelligence. By situating API manufacturers, branded marketers, and generic entrants in a shared analytical frame, the report helps teams assess where competitive intensity is rising, where branded products face substitution pressure, and where supply continuity may become a differentiator rather than a baseline expectation.
Conclusion: A Market Growing with Discipline, Competing with Complexity
The mesalazine market is moving from a phase of steady historical expansion into a period defined by procedural scrutiny, generic competition, and supply chain recalibration. That combination makes 2026 a pivotal year for strategic planning. Growth to 224.36 million USD in 2026 and a projected 3.7% CAGR through 2032 provide a credible foundation, but the real strategic work lies in understanding how dosage form preferences, application mix, regulatory events, and sourcing costs reshape value capture across regions and customer segments.
Mesalamine Market
Our full Mesalazine Market research report translates this complexity into a structured intelligence asset. It is built to support portfolio decisions, supply strategy, competitive positioning, and scenario planning with a level of detail that headline figures alone cannot provide. We invite you to access the complete report to obtain the segmentation depth, competitive mapping, and forward-looking analysis needed to turn market growth into disciplined execution.
For detailed analysis of this topic, please visit the official page: Mesalazine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China Smart Retail Market is set to witness impressive revenue growth, with total revenues advancing from $37,250 million in 2020 to $94,800 million by 2035. Key drivers include the expansion of digital infrastructure, proliferation of automated stores, and widespread implementation of data analytics and AI tools. The years 2025 and beyond are projected to experience accelerated growth rates as both consumer expectations and technological investments rise, cementing China's leadership in next-gen retail innovation.
Read More - https://bussinessinsights.com/research-report/china-smart-retail-market
Supermarkets/Hypermarkets lead the smart retail market in China in 2025, capturing 30% of the application segment, driven by their rapid adoption of digital and automated technologies. Convenience stores follow closely at 27%, benefiting from network expansion in both urban and rural regions. Specialty Stores account for 18%, reflecting consumer demand for tailored experiences, while Department Stores (12%), Drugstores/Pharmacies (7%), and Others (6%) supplement the market. This structure highlights China’s dynamic retail transformation, emphasizing customer experience, convenience, and product diversity.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-smart-retail-market
Frequently Asked Questions
Who are the key players in China Smart Retail Market industry?
The top five players in China’s Smart Retail Market include Alibaba Group, JD.com, Tencent Holdings, Suning.com, and Huawei. These firms drive innovation through AI, IoT, and automation, leading the integration of online-to-offline retail solutions, omnichannel experiences, and cutting-edge smart store technologies across mainland China.
What is the China Smart Retail Market growth?
The China Smart Retail Market is witnessing rapid growth, estimated at a CAGR of over 20% during 2023-2028. Recent advancements, like Alibaba's Freshippo expansion and JD.com's smart supply chain upgrades, are propelling market acceleration, driven by rising consumer digitalization and increased investment in automated retail infrastructure.
Which segment accounted for the largest China Smart Retail Market share?
Online retailing segment holds the largest share in China’s Smart Retail Market. E-commerce platforms led by Alibaba and JD.com dominate, capitalizing on extensive digital networks, mobile payments, and AI-driven personalization, offering consumers seamless purchase journeys and retailers advanced sales analytics for highly efficient customer engagement.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Arts & Crafts Market Hits $56.26B in 2025, 5.6% CAGR to $82.38B by 2032
By PW Consulting, 2026-09-16
Unlocking Strategic Value in the Arts and Crafts Market: A 2026 Executive Briefing
The global arts and crafts industry is entering a decisive inflection point. As organizations navigate a landscape shaped by post-pandemic normalization, shifting consumer behaviors, and evolving supply chain dynamics, the ability to anticipate market trajectories has become a critical differentiator. PW Consulting’s latest comprehensive research on the Arts and Crafts Market delivers the analytical rigor and forward-looking intelligence required to transform uncertainty into executable strategy. This briefing outlines the structural forces reshaping the sector, examines the competitive architecture, and demonstrates how decision-makers can harness our 2026–2032 forecast framework to secure sustainable growth in an increasingly fragmented landscape.
Macro Trajectory and Structural Demand Signals
The sector has demonstrated remarkable resilience over the past half-decade, defying broader macroeconomic headwinds that constrained discretionary spending in adjacent consumer categories. Drawing on a rigorous historical baseline spanning 2020 through 2025, our analysis maps a consistent expansion trajectory that sets the foundation for sustained momentum across the forecast horizon. The market has steadily grown from a baseline valuation in the early 2020s to a substantially elevated valuation by 2025, reflecting robust demand across both retail and commercial channels.
This upward trajectory is projected to continue through the end of the decade, with total market valuation anticipated to reach new milestones by 2032. The compound annual growth rate of 5.6 percent underscores a steady, compounding expansion rather than a speculative spike. For executives, this implies that arts and crafts is transitioning from a cyclical lifestyle segment into a structurally supported consumer and commercial category. The persistence of demand is further validated by independent spending indicators, which confirm that consumer outlays for non-essential creative products remained resilient throughout 2025 despite cooling labor markets and lingering inflationary pressures. This divergence from broader discretionary trends suggests deep-seated behavioral shifts: creative engagement is increasingly viewed as a core wellness and community-building driver rather than a discretionary luxury.
Yet macroeconomic stability alone does not dictate strategic advantage. The operational environment is being reshaped by material sourcing constraints, regulatory scrutiny, and channel fragmentation. Nearly a quarter of global manufacturers experienced production schedule delays during 2025 as supply chain disruptions impacted imported raw materials. Simultaneously, a significant portion of consumers reported dissatisfaction with non-certified products sourced through unverified digital marketplaces. These friction points reveal a market that is simultaneously expanding and maturing, where quality assurance, compliance readiness, and supply chain transparency are rapidly becoming competitive moats rather than baseline operational requirements.
Segmentation Architecture and Application Dynamics
Understanding where value concentrates is essential for resource allocation, product positioning, and channel strategy. Our research dissects the market across multiple structural dimensions, revealing distinct demand pools that operate under different velocity and margin profiles. In the product taxonomy, traditional creative mediums continue to command the largest share of revenue, anchored by painting and drawing applications that reflect enduring consumer preference for accessible, expressive formats. Sewing and fabric-based activities represent the next major pillar, benefiting from the sustained DIY and home textile revival. Paper crafts, kid-focused creative kits, specialized arts and crafts tools, and a broader category of ancillary offerings complete the ecosystem, each with unique seasonal patterns, demographic affinities, and retail pathway requirements.
The application split further clarifies strategic priorities. Personal use dominates overall consumption, reflecting the sector’s deep roots in hobbyist, educational, and mindfulness-driven engagement. Commercial applications, while smaller in relative scale, represent a high-value growth vector where institutional procurement, retail merchandising, and professional-grade material specifications create distinct pricing and service expectations. Companies that treat personal and commercial demand as interchangeable risk diluting their value proposition. Instead, successful operators are designing bifurcated product architectures, distribution partnerships, and compliance frameworks that align with the specific purchasing criteria of each application vertical.
Geographic distribution tells a parallel story of maturity and emerging opportunity. North America and Europe continue to anchor substantial portions of total revenue, supported by established retail infrastructure, strong brand recognition, and mature consumer education around creative products. Asia Pacific presents a structurally significant footprint, driven by expanding middle-class participation, localized manufacturing capabilities, and accelerating digital commerce penetration. Latin America and the Middle East and Africa, while smaller in absolute terms, reflect incremental growth vectors where population demographics, informal retail networks, and rising disposable income create early-stage expansion potential. Crucially, these regional profiles are not static; they are being reshaped by cross-border commerce, localized product adaptation, and shifting regulatory environments, requiring executives to move beyond one-size-fits-all geographic assumptions.
Competitive Landscape and Strategic Positioning
The industry’s competitive architecture is characterized by a moderate concentration profile, with the top three players collectively holding a modest share of total market revenue and the top five firms extending that footprint only slightly further. This fragmented baseline indicates that scale alone is insufficient for durable advantage. Instead, differentiation is increasingly driven by brand trust, product innovation cadence, channel agility, and compliance readiness.
Several established players exemplify the strategic postures defining the current cycle. Crayola LLC maintains a dominant position in the children’s creative expression segment, leveraging iconic product architecture and recent campaign-driven innovation such as its 2025 launch of a newly positioned 64-count crayon box designed to reinforce brand heritage while stimulating renewed retail velocity. Faber-Castell AG anchors its positioning in premium art and graphic materials, emphasizing professional drawing instruments and marker systems that cater to both serious hobbyists and educational institutions. STAEDTLER Mars GmbH & Co. KG operates across a broad spectrum of drawing and coloring instruments, with a long-standing reputation for precision engineering and durable creative tools. F.I.L.A. Group extends its footprint through modeling clays, crayons, and related creative products, with brand portfolios that bridge educational and artistic use cases. Newell Brands Inc. operates as a diversified portfolio player, integrating writing instruments, markers, and craft supplies across multiple recognized brand assets, enabling cross-category bundling and broad retail distribution.
These enterprises illustrate two divergent but complementary strategic playbooks. The first prioritizes category leadership within high-visibility product families, using brand equity, packaging innovation, and campaign-led demand generation to defend share and drive trial. The second emphasizes portfolio breadth, channel leverage, and operational scale to capture share across multiple sub-segments and retail formats. For market entrants and mid-tier operators, the strategic implication is clear: competing on volume alone against entrenched portfolios is inefficient. Sustainable positioning requires a clearly defined value narrative, whether anchored in premium material quality, educational alignment, demographic targeting, or supply chain reliability.
Operational Realities and Compliance Imperatives
Strategic planning in this sector must account for a growing layer of operational complexity. Regulatory frameworks are becoming more explicit, particularly in the United States, where manufacturers must align with chronic toxicity labeling requirements and toy safety standards before products reach retail shelves. Compliance is no longer a back-office function; it is a market access prerequisite that directly influences shelf eligibility, retailer confidence, and consumer trust. Organizations that embed regulatory readiness into product development cycles gain a distinct advantage in speed-to-market and risk mitigation.
Quality assurance is equally decisive. The proliferation of unverified online retail channels has introduced significant variability in product authenticity and material safety. Consumer dissatisfaction with non-certified supplies has become a material reputational and retention risk, particularly in categories where parents, educators, and professional creators prioritize predictable performance and safe material composition. Companies that invest in certification transparency, traceability systems, and channel vetting protocols are better positioned to defend margin integrity and reduce returns, while also building the trust capital necessary to expand into higher-value application segments.
Supply chain resilience represents a third operational imperative. Imported material dependencies have exposed production schedules to volatility, forcing manufacturers to reassess sourcing diversification, inventory buffers, and lead-time planning. The firms that treat supply continuity as a strategic capability, rather than a tactical procurement function, will be better equipped to protect launch calendars, maintain retail availability, and respond to demand spikes without compromising margin structure.
How This Research Converts Intelligence into Execution
PW Consulting’s Arts and Crafts Market report is engineered for decision-makers who require more than high-level trend commentary. The study integrates historical performance, forward-looking forecasts, and granular segmentation analysis into a single strategic framework designed to inform product roadmaps, channel investment, pricing architecture, and competitive positioning. Readers will gain access to structured evaluations of market sizing across multiple time horizons, enabling scenario planning that accounts for both base-case momentum and structural inflection points.
Arts and Crafts Market
The report provides a detailed segmentation map that clarifies how revenue distributes across product types, application contexts, and regional demand pools. Rather than presenting static share figures in isolation, the analysis ties each segment to underlying demand drivers, purchasing behavior patterns, and channel dynamics, allowing stakeholders to identify where incremental investment is likely to yield the strongest returns. Competitive profiling extends beyond corporate descriptions to examine strategic posture, product architecture, and market signaling, giving executives a practical lens for benchmarking their own positioning against incumbent playbooks.
Operational context is embedded throughout. Regulatory expectations, consumer quality perceptions, and supply chain friction points are evaluated not as peripheral risks but as strategic variables that influence product design, channel selection, and go-to-market timing. By connecting market structure to execution realities, the research enables teams to prioritize initiatives that are both commercially attractive and operationally feasible.
For organizations evaluating market entry, category expansion, or portfolio optimization, the study offers a structured basis for opportunity sizing and risk assessment. For incumbent players, it provides a diagnostic framework to pressure-test growth assumptions, identify vulnerable share pockets, and align innovation pipelines with the segments most likely to compound value over the forecast period.
Worldwide Harbor Craft Market
Strategic Imperatives for 2026 and Beyond
The next phase of growth in the arts and crafts sector will be defined by how effectively organizations translate market visibility into disciplined execution. Several priorities stand out. First, companies must calibrate portfolio investment to segment velocity rather than historical familiarity, recognizing that demand dynamics differ sharply between personal and commercial applications, as well as across product families. Second, brand trust and compliance readiness must be treated as revenue-enabling assets, particularly as channel fragmentation increases and consumer scrutiny around product safety intensifies. Third, supply chain design should be aligned with market expansion goals, ensuring that sourcing strategies, inventory planning, and launch sequencing can sustain availability during periods of demand acceleration.
Finally, competitive positioning requires honest segmentation of the playing field. With market concentration remaining moderate, the opportunity for targeted share capture exists, but it will accrue to organizations that define a clear value proposition, execute consistently across the chosen channel mix, and invest in the operational foundations that protect margin and reputation over time.
The full scope of our 2026–2032 analysis extends far beyond the directional signals outlined here. Detailed segmentation trajectories, competitive benchmarking, regional demand mapping, and scenario-based revenue pathways are available in the complete report. Executives seeking to convert market momentum into measurable strategic advantage are encouraged to access the full research suite, where the underlying intelligence is structured to support board-level planning, product strategy, and commercial execution with precision.
For detailed analysis of this topic, please visit the official page: Arts and Crafts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
China's security solutions market is projected to grow from USD 19,200 million in 2020 to USD 51,600 million by 2035. This remarkable rise is propelled by ongoing digitalization, mounting security challenges, and strong investments in both public and private sectors. The compound annual growth rate (CAGR) for the period 2025 to 2035 is estimated at approximately 10.1%, reflecting sustained technology adoption, urban expansion, and robust demand for advanced surveillance, access management, and integrated platforms.
Read More - https://bussinessinsights.com/research-report/china-security-solutions-market
Commercial applications hold the lion’s share (36%) of China’s security solutions market by application in 2025, as businesses prioritize safety against theft and cyber risks. Government and infrastructure projects contribute 21%, benefiting from large-scale public safety initiatives. Residential adoption stands at 18%, driven by smart home devices and rising urban incomes. Industrial (12%), transportation (8%), and healthcare (5%) complete the landscape. The dominance of the commercial and government segments highlights the country’s emphasis on robust security for public spaces, critical infrastructure, and corporate facilities.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-security-solutions-market
Frequently Asked Questions
Who are the key players in China Security Solutions Market industry?
The top five players in the China Security Solutions Market are Hikvision, Dahua Technology, Huawei, Uniview, and Zkteco. Hikvision and Dahua dominate in surveillance products, Huawei specializes in integrated security and network solutions, Uniview is a leader in IP video surveillance, and Zkteco is a top provider of biometric access control.
What is the China Security Solutions Market growth?
The China Security Solutions Market has experienced robust growth, with a CAGR of over 10% in recent years. In 2023, companies like Hikvision reported increased revenues driven by higher demand for smart surveillance and AI-based security systems across government, commercial, and residential sectors.
Which segment accounted for the largest China Security Solutions Market share?
Video surveillance remains the largest segment by application in the China Security Solutions Market, accounting for significant market share. This dominance is attributed to the mass adoption of CCTV, AI analytics, and network video monitoring in urban security, transportation, and critical infrastructure protection.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
Revenue for the China 4K technology market is projected to grow from USD 16,100 Million in 2020 to USD 51,400 Million by 2035. The growth is underpinned by rapid hardware upgrades, government-backed digital infrastructure, and the widespread shift to streaming and interactive display solutions. By 2025, the market is estimated to reach USD 28,500 Million, marking a significant leap, driven by evolving consumer preferences and accelerated technology adoption. Continued innovation is expected to sustain robust CAGR through the forecast period.
Read More - https://bussinessinsights.com/research-report/china-4k-technology-market
Consumer electronics stand as the primary application segment in the China 4K technology market, constituting 42% of total use in 2025. Entertainment & media claims 27%, closely followed by retail at 10%. The push for high-quality home entertainment and gaming notably boosts adoption, while healthcare, aerospace & defense, and education benefit from 4K’s clarity and operational value. Broader use across sectors is supported by expansive infrastructure and digital transformation initiatives throughout China.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-4k-technology-market
Frequently Asked Questions
Who are the key players in China 4K Technology Market industry?
The top 5 players in the China 4K Technology Market include Hisense, Xiaomi, TCL Corporation, BOE Technology Group, and Skyworth Group. These companies lead in innovations, production, and widescale adoption of 4K displays and TVs, leveraging their manufacturing capabilities and extensive distribution networks across China.
What is the China 4K Technology Market growth?
The China 4K Technology Market is experiencing robust growth, with a CAGR of over 19% from 2021 to 2024. Companies like Hisense have expanded 4K TV product offerings, and increased adoption in smart cities and education have fueled recent market acceleration.
Which segment accounted for the largest China 4K Technology Market share?
The consumer electronics segment, especially 4K televisions, dominates the China 4K Technology Market. With rising demand for high-resolution displays in home entertainment, this segment claimed the largest share due to widespread consumer adoption, supported by leading brands such as TCL and Xiaomi.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
The China Smart Retail Market is set to witness impressive revenue growth, with total revenues advancing from $37,250 million in 2020 to $94,800 million by 2035. Key drivers include the expansion of digital infrastructure, proliferation of automated stores, and widespread implementation of data analytics and AI tools. The years 2025 and beyond are projected to experience accelerated growth rates as both consumer expectations and technological investments rise, cementing China's leadership in next-gen retail innovation.
Read More - https://bussinessinsights.com/research-report/china-smart-retail-market
Supermarkets/Hypermarkets lead the smart retail market in China in 2025, capturing 30% of the application segment, driven by their rapid adoption of digital and automated technologies. Convenience stores follow closely at 27%, benefiting from network expansion in both urban and rural regions. Specialty Stores account for 18%, reflecting consumer demand for tailored experiences, while Department Stores (12%), Drugstores/Pharmacies (7%), and Others (6%) supplement the market. This structure highlights China’s dynamic retail transformation, emphasizing customer experience, convenience, and product diversity.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-smart-retail-market
Frequently Asked Questions
Who are the key players in China Smart Retail Market industry?
The top five players in China’s Smart Retail Market include Alibaba Group, JD.com, Tencent Holdings, Suning.com, and Huawei. These firms drive innovation through AI, IoT, and automation, leading the integration of online-to-offline retail solutions, omnichannel experiences, and cutting-edge smart store technologies across mainland China.
What is the China Smart Retail Market growth?
The China Smart Retail Market is witnessing rapid growth, estimated at a CAGR of over 20% during 2023-2028. Recent advancements, like Alibaba's Freshippo expansion and JD.com's smart supply chain upgrades, are propelling market acceleration, driven by rising consumer digitalization and increased investment in automated retail infrastructure.
Which segment accounted for the largest China Smart Retail Market share?
Online retailing segment holds the largest share in China’s Smart Retail Market. E-commerce platforms led by Alibaba and JD.com dominate, capitalizing on extensive digital networks, mobile payments, and AI-driven personalization, offering consumers seamless purchase journeys and retailers advanced sales analytics for highly efficient customer engagement.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Non-Destructive Testing Instruments Market to Reach $30.7B by 2032, 9.3% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Non-Destructive Testing Instruments Market: Navigating Growth Through 2032
The global landscape for non-destructive testing instruments is undergoing a profound transformation, driven by escalating safety mandates, infrastructure aging, and the rapid integration of digital technologies. As industrial sectors worldwide prioritize asset integrity and operational reliability, the demand for advanced inspection solutions has accelerated beyond historical trajectories. Our latest comprehensive analysis, Non-Destructive Testing Instruments Market, provides a critical roadmap for stakeholders aiming to align their strategies with the compounding opportunities projected through 2032. This article outlines the strategic value of this research, synthesizing macroeconomic indicators, competitive dynamics, and emerging industry shifts to underscore why informed decision-making is paramount in the current fiscal year and beyond.
For enterprise leaders, investors, and product strategists, the overarching market narrative is defined by sustained expansion and evolving technological prerequisites. Historical data reveals a consistent upward momentum, with the market valuation climbing from 11.6 billion USD in 2020 to an estimated 16.5 billion USD by 2025. This trajectory is not merely a reflection of post-pandemic recovery but indicative of a structural shift in how industries approach quality assurance and risk mitigation. The forecast period anticipates a robust compound annual growth rate of 9.3 percent, propelling the market valuation toward 18.62 billion USD in 2026 and surpassing the 30 billion USD threshold by 2032. Such figures underscore a fertile environment for capital allocation, product development, and strategic partnerships. However, realizing value within this ecosystem requires navigating a complex web of regional variances, technological bifurcation, and regulatory tightening that only deep-dive intelligence can adequately decode.
Deconstructing the Market Architecture
A superficial glance at aggregate numbers offers limited strategic utility. True competitive advantage lies in understanding the granular mechanics that drive revenue streams across different modalities, end-user sectors, and geographic territories. The research provides a multi-dimensional segmentation analysis that illuminates where growth is concentrated and which sub-markets are maturing versus those poised for disruption.
Technological Modalities and Adoption Curves
The industry is characterized by a diverse array of testing methodologies, each serving distinct operational needs and capital constraints. Ultrasonic testing continues to command significant attention, reflecting its versatility in detecting internal flaws across a wide range of materials without causing damage. Radiographic testing maintains its relevance, particularly in scenarios demanding high-resolution imaging for complex geometries. Simultaneously, magnetic particle testing, eddy current testing, and emerging alternative types cater to specialized applications where surface defects, conductivity variations, or specific material properties are the primary concern.
Non-Destructive Testing Instruments Market
The strategic nuance here is not just in identifying the dominant techniques but in understanding the shifting cost-benefit analyses that influence procurement decisions. High upfront costs associated with advanced instruments, such as phased array ultrasonic and digital radiography systems, remain a barrier for small and medium enterprises. Yet, the pressure on component and sensor pricing is reshaping the affordability landscape. Our analysis dissects these pricing dynamics, average selling price trends, and the subtle trade-offs between capital expenditure and long-term inspection efficacy, enabling organizations to forecast budget requirements and technology roadmaps with precision.
Sectoral Demand Drivers
Demand for NDT instruments is inextricably linked to the operational intensity and safety criticality of downstream industries. The oil and gas sector remains a pillar of consumption, driven by the need to monitor pipelines, refineries, and offshore structures under harsh conditions. Power generation facilities, encompassing both traditional and renewable energy assets, rely heavily on inspection technologies to ensure grid stability and prevent catastrophic failures. Aerospace applications impose the most rigorous standards, where the margin for error is non-existent and regulatory compliance is absolute. Manufacturing, as a broad category, continues to expand its footprint, integrating NDT into production lines for real-time quality control. Other applications further diversify the revenue base, capturing niche but high-growth opportunities in automotive, rail, and marine sectors.
The report delves into the specific demand catalysts within each vertical, highlighting how operational downtime costs, regulatory penalties, and the push for predictive maintenance are reshaping procurement behaviors. By mapping these application-specific drivers, decision-makers can identify high-engagement segments and tailor their value propositions accordingly.
Geographic Value Distribution
Regional dynamics play a pivotal role in shaping market opportunities. North America and Europe represent mature markets with established regulatory frameworks and high adoption rates of advanced technologies. Asia Pacific, while currently reflecting a different scale of valuation, is emerging as a critical growth engine fueled by rapid industrialization, infrastructure development, and increasing awareness of quality standards. Latin America and the Middle East and Africa contribute distinct regional profiles, often tied to resource extraction, energy projects, and localized manufacturing hubs.
The research avoids generic regional summaries, instead providing a nuanced view of how economic policies, trade dynamics, and local industrial priorities influence market penetration. Understanding these geographic nuances is essential for multinational corporations seeking to optimize their distribution networks and for regional players aiming to capture cross-border opportunities.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderately concentrated structure, with a select group of leading entities commanding a significant share of total revenue. The top three competitors account for approximately 65.5 percent of the market, while the top five collectively hold around 82.2 percent. This concentration indicates the presence of established incumbents with strong technological portfolios, extensive service networks, and deep customer relationships. However, the remaining market share is distributed among a diverse array of specialized firms, creating a dynamic environment where innovation and niche expertise can disrupt traditional hierarchies.
Profiles of Key Industry Participants
The competitive arena is populated by organizations that have carved out distinct identities through technological specialization, geographic reach, and service integration. Mistras Group, Inc., headquartered in Princeton Junction, New Jersey, stands as a leading provider of NDT instruments and field inspection solutions, offering ultrasonic and advanced testing equipment tailored for industrial applications. Olympus Corporation, based in Shinjuku, Tokyo, is a major manufacturer focusing on ultrasonic phased array and thickness measurement systems, leveraging decades of imaging and sensing expertise.
Nikon Metrology NV, located in Tricht, Belgium, supplies X-ray and computed tomography instruments that cater to precision NDT applications, appealing to sectors where detailed internal visualization is paramount. Sonatest Ltd, operating from Hertfordshire, UK, produces portable ultrasonic and eddy current NDT instruments, addressing the need for field-deployable and flexible testing solutions. Acuren Corp., based in Markham, Ontario, Canada, provides advanced NDT equipment and inspection services, with a specialization in phased array and digital radiography instruments that bridge hardware and expertise.
Eddyfi Technologies, from Quebec City, Quebec, develops eddy current and remote NDT instruments specifically designed for pipeline and industrial use, emphasizing reliability in critical infrastructure monitoring. Zetec Inc., situated in San Jose, California, manufactures eddy current and magnetic particle NDT instruments, serving a broad customer base with robust and proven technologies. YXLON International GmbH, headquartered in Hamburg, Germany, produces X-ray NDT instruments and modules, contributing to the radiographic testing ecosystem with high-performance solutions. Fischer Technology Inc., located in Windsor, Connecticut, supplies coating thickness and material analyzers used in NDT contexts, addressing surface measurement and material verification needs. TWI Ltd, based in Cambridge, UK, provides advanced NDT testing instruments and systems for research and industrial use, acting as a bridge between cutting-edge development and practical deployment.
Recent Corporate Developments and M&A Activity
The competitive landscape is further shaped by a series of strategic moves that signal shifting priorities and consolidation trends. In April 2026, NDT Systems launched the BondHub Imaging Bond Tester with C-scan imaging capability, a product release that enhances composite inspection capabilities and reflects the growing emphasis on advanced imaging for non-metallic structures. This development underscores the industry's pivot toward multi-modal inspection tools that deliver actionable data faster.
Earlier in the forecast window, SGS introduced a new AI-driven inspection platform in November 2025, designed to enhance NDT accuracy through machine learning algorithms and automated defect recognition. This launch highlights the accelerating integration of artificial intelligence into inspection workflows, promising to reduce human error and increase throughput. In October 2025, Bureau Veritas executed an acquisition of a regional competitor to expand its advanced ultrasonic testing capabilities, a move that illustrates the strategic value of consolidating technological strengths and expanding service footprints.
Intertek entered a strategic partnership in September 2025 with a technology firm to develop a remote digital NDT inspection platform, signaling the industry's embrace of connectivity and remote monitoring. Such collaborations are becoming increasingly common as organizations seek to leverage external expertise and accelerate digital transformation. Additionally, Previan Technologies realigned Eddyfi Technologies and NDT Global as independent industrial-technology leaders in June 2026, a corporate restructuring that aims to sharpen focus and enhance agility within specialized segments of the market.
X-ray Non-destructive Testing Equipment Market
Industry Dynamics and Headwinds
Regulatory Evolution and Compliance Costs
Regulatory frameworks are tightening, with direct implications for both equipment suppliers and inspection service providers. The new ISO 9712-2025 standard, issued by ISO Technical Committee 135 in January 2026, increases the certification renewal frequency for NDT personnel to every three years, mandating compulsory retraining on advanced methods. This shift ensures that the workforce remains proficient with evolving technologies but also introduces recurring compliance costs and administrative burdens. Similarly, the EN 4179:2026 standard establishes updated minimum requirements for the qualification and certification of NDT personnel in aerospace applications, reinforcing the sector's demand for highly credentialed inspectors.
These regulatory changes elevate the importance of instrumentation that supports efficient training, certification, and documentation. Instruments that integrate with digital record-keeping systems or offer intuitive interfaces for complex procedures gain a competitive edge in an environment where compliance is non-negotiable. Furthermore, certification renewal changes in 2026 require more frequent retraining, driving up labor costs for qualified NDT personnel, as noted by industry sources in late 2025. This labor cost pressure incentivizes the adoption of tools that maximize inspector productivity and reduce the time required per inspection.
Cost Pressures and Adoption Barriers
Despite the favorable growth outlook, cost remains a pivotal factor influencing market penetration, particularly among smaller enterprises. The high upfront cost of advanced NDT instruments, including phased array ultrasonic and digital radiography systems, continues to limit adoption among small and medium enterprises. This barrier creates a bifurcation in the market, where large industrial players can accelerate their digital and advanced testing transformation, while smaller entities may rely on traditional methods or shared service models.
On the pricing front, averaged selling price trends for ultrasonic testing techniques showed increases through 2024, with ongoing pressure from component and sensor pricing in 2025. These dynamics suggest that manufacturers are navigating a delicate balance between maintaining margins and offering competitive pricing in a supply-constrained environment. Our analysis examines how these cost structures affect downstream pricing strategies and the total cost of ownership for end-users, providing clarity on where economies of scale can be leveraged and where value-added services can offset hardware costs.
Strategic Value of the Research for 2026 Decision-Making
In an environment defined by rapid technological change, regulatory evolution, and intense competitive maneuvering, access to granular, forward-looking intelligence is a strategic necessity. This research equips decision-makers with the analytical framework required to navigate uncertainty and capitalize on emerging opportunities.
Capital Allocation and Investment Strategy
For investors and corporate strategy teams, the forecast trajectory offers a compelling basis for portfolio decisions. The projected growth from 18.62 billion USD in 2026 to over 30 billion USD by 2032 indicates sustained demand across multiple cycles. Understanding which segments are expanding at higher rates, which technologies are gaining share, and which geographic regions are accelerating adoption allows for targeted investment in high-potential areas. The report's segmentation analysis helps identify where capital can be deployed with the highest return potential, whether in product innovation, market expansion, or strategic acquisitions.
Product Development and Technology Roadmapping
For manufacturers and technology developers, the research provides critical insights into the evolving requirements of end-users. The shift toward AI-driven platforms, remote digital inspection capabilities, and advanced imaging solutions signals where R&D efforts should be concentrated. By analyzing recent product launches and corporate realignments, organizations can benchmark their own innovation pipelines and identify gaps in the market. The discussion of cost pressures and pricing trends further informs go-to-market strategies, helping companies position their offerings to address both the premium segment seeking cutting-edge performance and the cost-conscious segment requiring accessible solutions.
Market Entry and Competitive Positioning
For companies considering market entry or expansion, the competitive landscape analysis offers a realistic assessment of the barriers and opportunities. The concentration of market share among top players highlights the importance of differentiation, whether through technological novelty, specialized application focus, or regional expertise. The profiles of key companies and recent strategic developments reveal the tactics that incumbents are employing to defend and grow their positions. Armed with this knowledge, new entrants can identify underserved niches, form strategic alliances, or develop disruptive business models that challenge the status quo.
Risk Management and Regulatory Compliance
For operators and service providers, the regulatory updates represent both a challenge and an opportunity. The increased frequency of certification renewals and the heightened requirements for advanced methods underscore the need for robust training programs and compliant instrumentation. The research integrates these regulatory dynamics into the broader market context, helping organizations anticipate compliance costs, plan workforce development, and select tools that streamline certification and documentation processes. By proactively addressing these factors, companies can mitigate operational risks and maintain their competitive standing in regulated industries.
Conclusion: The Path Forward
The Non-Destructive Testing Instruments Market is at an inflection point, where historical growth patterns are being amplified by technological innovation, regulatory tightening, and the imperatives of asset integrity across critical industries. The data landscape reveals a market on a robust growth trajectory, yet the true value for decision-makers lies in the strategic insights that connect macroeconomic trends to actionable business implications. This research serves as a comprehensive guide for navigating the complexities of the market, offering the depth and precision required to make informed investments, drive product innovation, and secure a resilient competitive position.
To fully capitalize on the opportunities outlined in this analysis, stakeholders are encouraged to access the complete report. The full study provides the detailed segmentation data, granular regional breakdowns, company-level assessments, and forward-looking scenarios that form the backbone of a winning strategy. By integrating this intelligence into your planning processes, you can transform market uncertainty into a structured pathway for sustainable growth and leadership in the years ahead.
For detailed analysis of this topic, please visit the official page: Non-Destructive Testing Instruments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
China Automatic Identification and Data Capture Market Outlook & Forecast
By supriya singh , 2026-09-16
China’s AIDC market revenue shows a consistent upward trajectory from 2020 through 2035. In 2025, the market size hits USD 3,200 Million, reflecting growing investments and widespread adoption in key verticals. The market is projected to reach a significant USD 8,700 Million by 2035, with compound annual growth fueled by expansions in automation, smart city solutions, and healthcare digitalization. Major players continue to innovate, introducing scalable and cost-effective systems that propel the adoption curve further, ensuring AIDC remains a critical infrastructure element in China’s transformative journey.
Read More - https://bussinessinsights.com/research-report/china-automatic-identification-and-data-capture-market
By application, the retail sector captures the largest share of the China AIDC market in 2025 at 30%, as e-commerce and omnichannel strategies surge in urban centers. Manufacturing is the second-largest segment with a 24% share, focusing on automated production tracking and supply chain transparency. Healthcare commands an 18% share, leveraging AIDC for patient, drug, and equipment management. Other sectors including banking & finance, transportation & logistics, and government utilize these technologies to drive compliance, efficiency, and citizen services, underscoring the pervasive integration of automatic identification and data capture solutions across China’s growing economy.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-automatic-identification-and-data-capture-market
Frequently Asked Questions
Who are the key players in China Automatic Identification and Data Capture Market industry?
The top 5 players in the China Automatic Identification and Data Capture (AIDC) market are Zebra Technologies, Honeywell International, Datalogic, SICK AG, and Newland Auto-ID. These companies dominate through advanced barcode scanners, RFID solutions, and data management technologies tailored for China’s retail, logistics, and manufacturing sectors.
What is the China Automatic Identification and Data Capture Market growth?
The China AIDC market is experiencing robust growth, estimated at a CAGR of over 12% (2023-2028). Recent expansion is driven by growing adoption of smart logistics and e-commerce automation. For instance, Alibaba has integrated advanced AIDC solutions to streamline warehouse and supply chain operations.
Which segment accounted for the largest China Automatic Identification and Data Capture Market share?
The retail and e-commerce segment accounted for the largest market share in China’s AIDC market. This is due to surging online shopping activities and the need for efficient inventory management, order fulfillment, and contactless payments, which have been rapidly adopted by companies like JD.com and Alibaba.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Cockpit and Flight Data Recorder Market Hits $170M in 2025, 5.8% CAGR to $257M by 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Cockpit Voice and Flight Data Recorder Market: Navigating Growth and Regulatory Shifts Through 2032
The aviation safety ecosystem stands at a pivotal juncture. As aircraft design philosophies evolve and regulatory bodies tighten mandates around data retention and crashworthiness, the Cockpit Voice and Flight Data Recorder market is experiencing a structural realignment that will define procurement strategies, product development roadmaps, and competitive positioning for the next decade. Our latest market research offers a comprehensive, data-driven blueprint for executives, sourcing directors, and engineering leaders who must make capital allocation and compliance decisions in 2026 and beyond.
This publication arrives at a moment when the intersection of technological innovation and regulatory compliance is no longer a peripheral concern, but a central boardroom priority. The insights contained within are designed to transform uncertainty into actionable intelligence, enabling stakeholders to anticipate demand shifts, evaluate supplier capabilities, and align investment timing with the market’s most consequential inflection points.
Market Trajectory: A Decade of Calculated Expansion
Tracing the historical arc from 2020 through 2025 reveals a market that has consistently demonstrated resilience and steady upward momentum, even amid global supply chain disruptions and shifting fleet utilization patterns. The sector has progressed from a baseline valuation in the early 2020s to a substantially expanded footprint by 2025, reflecting sustained airframe deliveries, replacement cycles, and the gradual integration of next-generation recording architectures across both commercial and defense platforms.
Looking forward across our forecast period, the trajectory points toward continued growth, underpinned by heightened safety mandates, fleet modernization programs, and the ongoing proliferation of digital flight data streaming capabilities. The compound annual growth rate projected for this window signals a durable expansion narrative, one that will reward organizations capable of aligning their product portfolios and supply chain strategies with emerging compliance requirements. Critically, the projected valuation milestones across successive forecast years illustrate a market that is not merely expanding in nominal terms, but evolving in complexity, demanding more sophisticated integration, certification readiness, and lifecycle support capabilities from manufacturers and integrators alike.
For enterprise decision-makers, this growth profile carries strategic weight. It suggests that the market will accommodate new entrants and incumbent expansions alike, but that the distribution of opportunity will be uneven. Organizations that treat the recorder segment as a commoditized afterthought risk ceding ground to competitors who recognize it as a high-value, regulation-sensitive domain with significant barriers to entry and long-term revenue visibility.
Regulatory Catalysts Reshaping Demand Profiles
The single most potent force currently restructuring procurement pathways is the regulatory environment. Throughout 2024 and 2025, authorities across major aviation markets moved to codify extended recording durations and enhanced data accessibility standards. A landmark development in early 2026 saw the finalization of a rule mandating twenty-five-hour cockpit voice recorder retention for newly manufactured aircraft across multiple operational categories, with compliance timelines anchored to production dates in mid-2025. This ruling does not merely extend a specification; it fundamentally alters the engineering requirements for manufacturers designing for the commercial airliner, business jet, and commuter segments.
Complementary legislative actions, including provisions embedded in broader aviation reauthorization frameworks, have extended similar twenty-five-hour capability requirements to larger transport-category aircraft and established retrofit compliance horizons extending toward the end of the decade. These mandates create a dual-layer demand structure: an immediate pull from new production lines adapting to revised certification baselines, and a deferred but substantial pull from in-service fleets that must be upgraded or replaced to remain compliant. International standardization efforts have reinforced this trajectory, with global aviation bodies advancing proposals to harmonize flight recorder data download interfaces, reduce analysis friction, and improve cross-manufacturer interoperability. Such initiatives signal a longer-term shift toward data-centric safety architectures that will influence procurement criteria well beyond the current forecast horizon.
For organizations evaluating market entry, product line expansion, or supplier partnerships, the regulatory calendar is not a peripheral detail. It is a scheduling mechanism that dictates certification timelines, production slot allocation, retrofit campaign planning, and ultimately, revenue realization. The strategic implication is clear: companies that map their development cycles and capacity investments against these regulatory milestones will secure competitive advantage, while those that treat compliance as an after-the-fact engineering task will face costly redesigns and delayed market access.
Aerospace and Marine Data Recorders Market
Product Segmentation and Engineering Evolution
The market’s product architecture spans distinct recorder categories, each carrying different engineering demands, certification pathways, and end-user value propositions. Traditional flight data recording units continue to serve as the backbone of operational monitoring and accident investigation, while cockpit voice recording systems have undergone a generational leap in capacity and reliability. The emergence of combined voice and flight data recorder solutions reflects a broader industry preference for integrated, weight-optimized, and simplified installation architectures, particularly in platforms where space, power, and maintenance access are tightly constrained.
Engineering sophistication in this segment has accelerated markedly. Modern recorder families now emphasize extended recording durations, enhanced crashworthiness and fire resistance, faster data retrieval through advanced interface protocols, and optional onboard streaming or rapid-retrieval capabilities that reduce post-event analysis timelines. Ethernet-enabled download pathways, integrated rapid-retrieval information processing systems, and modular designs that accommodate multi-platform certification are increasingly becoming baseline expectations rather than premium differentiators. For integrators and airframe manufacturers, these features translate into reduced certification complexity, streamlined maintenance workflows, and improved alignment with fleet-wide data management strategies.
The implication for market participants is that product differentiation is shifting from standalone recorder specifications toward ecosystem compatibility. Suppliers that can demonstrate seamless integration with existing avionics suites, provide clear retrofit pathways, and offer lifecycle support aligned with extended operational use cases will capture disproportionate share in a market where total cost of ownership and compliance assurance weigh heavily in purchasing decisions.
Cockpit Voice and Flight Data Recorder Market
Competitive Architecture: Who Holds the Edge
The competitive landscape is defined by a concentrated group of established aerospace and defense technology firms that have invested heavily in recorder platforms, certification portfolios, and OEM relationships. Industry analysis indicates a market structure where a relatively small number of participants command a substantial share of revenue, reflecting the high technical barriers, lengthy certification cycles, and long-term supply agreements that characterize this domain. Such concentration rewards companies with proven track records in airworthiness certification, production scalability, and global aftermarket support.
Among the organizations shaping this competitive environment, several stand out for their product architectures and strategic positioning. Honeywell Aerospace has solidified its presence through combined recorder platforms engineered for commercial airliners and business jets, with certification coverage that spans multiple aircraft categories and recording durations aligned with the latest mandates. Curtiss-Wright Defense Solutions contributes through its recording technology divisions, including collaborative development of next-generation recorder series and proprietary systems designed for commercial aviation applications. Universal Avionics has advanced the segment through its fifth-generation recorder line, emphasizing combined unit configurations, Ethernet download options, and modular rapid-retrieval capabilities that align with modern fleet data management needs.
L3Harris Technologies maintains a strong footprint through its recorder and survival recorder families, including series designed for widely deployed airframes with supplemental type certificate coverage on platforms such as the Boeing 737NG and integrated rapid-retrieval systems. HENSOLDT brings European certification expertise and a portfolio spanning combined recorders, standalone flight data units, and voice recording models certified to recognized industry standards. Flight Data Systems has carved a position around lightweight combined recorder designs that meet stringent crashworthiness and fire-resistance requirements while offering optional rapid-retrieval integration. Safran extends its influence through helicopter and fixed-wing recorder solutions, reflecting the diversification of platform requirements across rotorcraft and general aviation segments. Acron Aviation has emerged as a notable player through its recorder series offering extended audio and flight data retention, alongside strategic recognition as an approved solution for major airframer programs and a platform for continuous online procurement of certified avionics components.
The strategic takeaway for procurement and planning teams is that supplier selection increasingly hinges on more than unit pricing. Certification breadth, retrofit readiness, production capacity, global support infrastructure, and alignment with forthcoming data interface standardization all factor into long-term value. Organizations that conduct structured supplier evaluations against these criteria will be better positioned to secure reliable supply, navigate certification dependencies, and capitalize on retrofit and replacement cycles.
Where 2026 Decision-Makers Must Focus
As enterprises calibrate their strategies for the current year and beyond, several priority areas demand focused attention. First, regulatory mapping must become a continuous function rather than a periodic compliance exercise. The staggered compliance dates across new production and retrofit mandates require organizations to sequence procurement, engineering, and fleet planning activities with precision. Second, product evaluation frameworks should incorporate data accessibility, interface compatibility, and aftermarket support as core criteria, reflecting the longer-term shift toward integrated safety data ecosystems.
Third, supply chain resilience warrants heightened scrutiny. The concentration of market share among a limited set of manufacturers underscores the importance of qualifying alternate sources where feasible, securing multi-year agreement structures, and stress-testing production capacity against anticipated demand surges driven by retrofit campaigns and fleet renewal programs. Fourth, forward-looking investment decisions should account for the possibility that standardization initiatives around data download interfaces and interoperability will create new value pools in software, analytics, and service delivery, extending the commercial relevance of recorder platforms beyond hardware sales.
Organizations that embed these considerations into their strategic planning will not only mitigate compliance risk but also unlock opportunities to influence specification development, secure preferred supplier status, and align product roadmaps with the market’s most consequential growth vectors.
What the Full Study Delivers
Our complete market research publication provides a granular, actionable foundation for the decisions outlined above. The report constructs a multi-year market size framework anchored to historical performance data and extended through a detailed forecast horizon, enabling precise scenario planning and investment timing analysis. It decomposes demand across major geographic markets and application segments, illuminating where growth concentration is forming and how regional aviation activity, fleet composition, and regulatory adoption patterns shape local opportunity profiles.
The study delivers deep segmentation analysis by recorder type, clarifying the relative commercial weight of flight data recorders, cockpit voice recorders, and combined systems, while mapping product architecture trends, certification requirements, and technological adoption curves across each category. Application-level examination distinguishes between civil aviation and military aviation demand drivers, including fleet renewal cycles, operational mandates, and platform-specific engineering requirements that influence procurement timing and specification preferences.
A dedicated competitive profiling section evaluates the strategic posture, product capabilities, certification footprints, and recent developments of the leading manufacturers, providing a structured basis for supplier benchmarking, partnership evaluation, and competitive positioning analysis. The report also integrates regulatory trackers, recent product launches, partnership announcements, and procurement developments, offering a continuously updated view of the forces that are actively reshaping purchasing requirements and market access conditions.
For executives seeking to validate capital allocation, guide engineering investment, or refine market entry strategies, the full study translates macro-level trends into specific, segment-level intelligence that can be operationalized across procurement, product management, and strategic planning functions. The most consequential details, including precise regional revenue distributions, application-level valuation breakdowns, and company-specific market share estimates, are reserved for the complete report to ensure that stakeholders receive unfiltered, decision-ready intelligence when they engage directly with the analysis.
The Strategic Case for Early Engagement
The Cockpit Voice and Flight Data Recorder market will not be defined solely by airframe production volumes or cyclical procurement patterns. It will be shaped by the interplay of regulatory mandates, engineering standardization, supplier concentration, and the growing expectation that safety recorders function as integral nodes within broader aviation data architectures. Organizations that act early to align their strategies with these forces will secure advantages in specification influence, supply assurance, and market positioning that will compound as the forecast period unfolds.
This research publication is designed to provide the evidentiary foundation and analytical structure necessary to make those decisions with confidence. By combining historical validation, forward-looking modeling, competitive mapping, and regulatory tracking into a single integrated framework, it equips decision-makers with the clarity required to navigate a market that rewards preparedness and penalizes ambiguity. The complete dataset, segment-level breakdowns, and detailed company assessments are available through the full report, offering the depth required to translate strategic intent into executed action.
For detailed analysis of this topic, please visit the official page: Cockpit Voice and Flight Data Recorder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The market revenue for battery monitoring systems in China is set for robust growth between 2020 and 2035. The sector is forecast to expand from $900 Million in 2021 to $2,200 Million by 2035, reflecting rapid adoption in mobility, infrastructure, and renewables. Government policy support, urban electric vehicle deployment, and ongoing grid modernization projects are central to this momentum. Periodic surges in investment and new technological introductions contribute to a stable upward trajectory in annual revenues.
Read More - https://bussinessinsights.com/research-report/china-battery-monitoring-system-market
Automotive applications are projected to account for the largest portion of the China Battery Monitoring System Market by 2025, reflecting the explosive growth of electric vehicles and hybrid powertrains in the region. Telecommunications and energy storage also command notable shares, as reliable backup and uninterrupted power remain paramount. Data centers and industrial uses are driving the adoption of advanced BMS, driven by expanding digital and manufacturing infrastructure. These trends highlight the strategic transition of battery monitoring from legacy utilities toward next-generation mobility and digital industries.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-battery-monitoring-system-market
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com